Industrial & Warehouse Insurance
Property and liability for distribution centers, logistics, flex, and industrial portfolios.
By Dan Wentz, commercial real estate insurance broker · Updated
Industrial is the asset class everyone wants to own, and underwriters still read it hard.
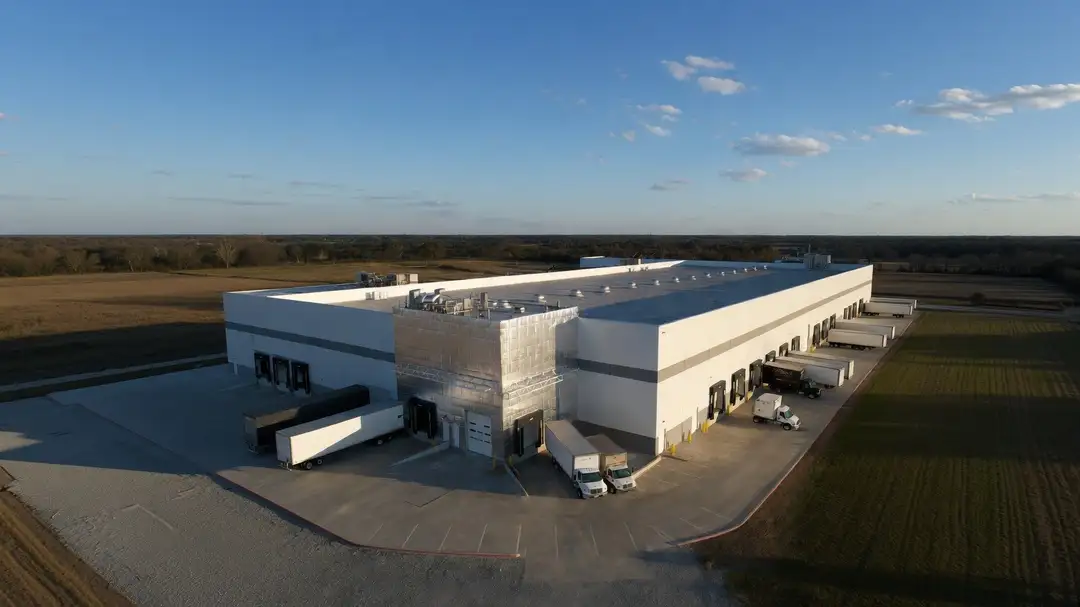
A single big-box distribution building can put $100M of insured value under one roof, which means the sprinkler design, the protection class, and what's actually stored inside get scrutinized before anyone offers a limit. Get those details right in the submission and capacity shows up. Get them wrong and you're buying layers at a worse price.
Who this is for
Built for accounts like yours
Coverage
What we structure
Property (high TIV)
Large sprinklered buildings with the protection and valuation detail that lets a carrier hold real capacity.
General liability
Premises and tenant-operations liability for logistics and industrial use.
Lessor's risk / NNN
Owner programs for single-tenant net-leased industrial, coordinated with the tenant's coverage.
Umbrella / excess
Excess towers for fleet, tenant, and contractual exposure.
Tools & guides
Tools and guides for this asset class
Free tool
Coinsurance Penalty Calculator
Free, no email required: a coinsurance clause cuts every claim, not just a total loss, when the limit trails replacement cost. See the exact payout on your loss, the penalty across loss sizes, and what it takes to cure the gap, plus the margin clause that replaces it on blanket programs.
Run your numbersGuide
Replacement Cost Value Guide
Why your limit should be built on what it costs to rebuild, not what the building would sell for, how that number is calculated, and how a stale one shrinks every claim under a coinsurance clause.
Read the guideGuide
Certificate of Insurance Guide
What a COI does and doesn't do, additional insured endorsements, and a checklist for reviewing the certificate a contractor hands you.
Read the guideFAQ
Common questions
Can you place a high-TIV single distribution building?
Yes. A single big-box can carry $100M+ of insured value, and whether one carrier takes it or we layer it comes down to the sprinkler and protection story in the submission. We build that story properly so underwriters can say yes at a number that works.
Do you write lessor's risk only (NNN) industrial?
We do. For single-tenant net-leased industrial we structure an owner's program that lines up with the tenant's coverage and the lender's requirements, without paying twice for the same risk.
What size accounts do you take?
Roughly $50,000 and up in annual premium, from one building to a multi-state industrial portfolio.
Coverage described on this page is a general summary, not a quote, coverage recommendation, or offer of insurance. Requesting a quote doesn't bind coverage. Terms, exclusions, and availability vary by carrier, state, and property, and only the policy actually issued determines coverage. Insurance is placed through producers licensed in the state where the property is located.
Free renewal review
Talk to a industrial & warehouse specialist
We'll reply within one business day with when to start marketing it and what to have ready. Built for accounts with $50,000+ in annual premium.
- A second set of expert eyes on your program, free.
- Marketed to the carriers that actually want your risk.
- No obligation, fully confidential.
Book 20 minutes or call (205) 999-4884