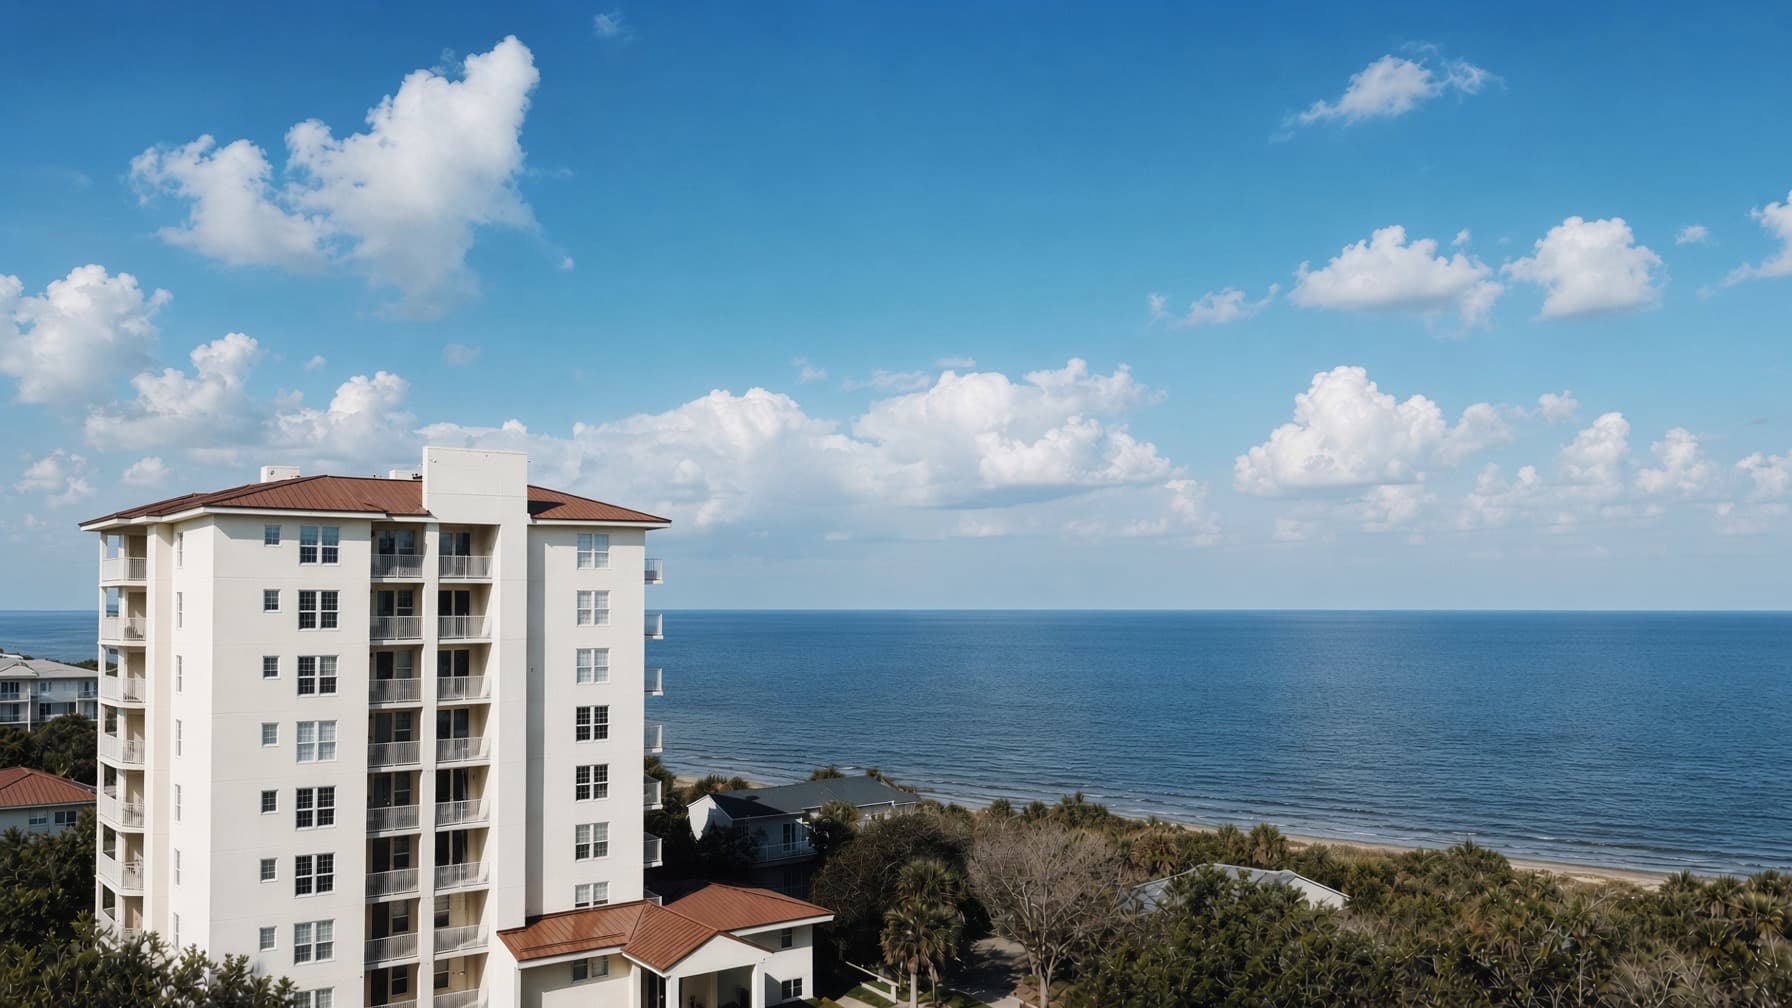
Condo association insurance for Gulf Shores and Orange Beach, Alabama
Named storm, wind, and flood programs for Baldwin County condominium associations, built around the deductible.
The short answer
Gulf Shores and Orange Beach condo associations buy wind coverage from E&S and London markets, the Alabama Insurance Underwriting Association, or both, and the named storm deductible is usually the largest number in the program. Size the deductible against your reserves, price flood alongside wind, and document roof and building condition before renewal. We are based in Birmingham, Alabama and place accounts with $50,000 or more in annual premium.
General information, not legal, tax, or coverage advice. What's covered depends on your specific policy wording, and the policy controls. Current as of October 2026.
What is the biggest insurance risk for a Gulf Shores or Orange Beach condo association?
The named storm deductible. Wind coverage on the Alabama Gulf Coast usually carries a percentage deductible tied to the building’s insured value, commonly starting around 5%. On a $60 million tower, 5% is $3 million the association pays before the carrier does, and whatever reserves don’t cover goes to owners as a special assessment. Model it for your building in the wind deductible calculator and read how a buy-down can shrink it.
What did Hurricane Sally show Baldwin County associations?
Hurricane Sally made landfall at Gulf Shores on September 16, 2020 as a Category 2 hurricane with 105 mph winds, moving at less than 5 mph. The National Weather Service in Mobile reported 3 to 6 feet of storm surge inundation across much of the area, 7 to 9 feet in the back bays and sounds of southeast Baldwin County, and 15 to 30 inches of rain, with 29.99 inches recorded in Orange Beach (NWS Mobile).
For a board, the lesson is that a slow storm produces wind, rain, and water losses in the same event, and they sit on different policies. Wind and flood have separate deductibles and separate limits. We size them together so the association knows its combined retention before hurricane season, not after.
Who writes wind coverage for Gulf Shores and Orange Beach condos?
Standard carriers write little wind this close to the water. Associations typically end up with surplus lines (E&S) and London market capacity, the Alabama Insurance Underwriting Association (AIUA), or both. The AIUA, known as the “Beach Pool,” began offering wind and hail only policies in 2001 for property south of the 31st parallel in Baldwin and Mobile counties, aimed at owners who cannot get coverage from a standard insurer (Alabama Department of Insurance). Eligibility and limits for a large association building are set by the AIUA, so confirm them before you plan around it.
A layered program, with primary and excess wind from more than one carrier, keeps any single carrier’s appetite from capping your limit. Our catastrophe and coastal property program explains how those layers are built.
Does FORTIFIED help a Gulf Shores or Orange Beach condo association?
FORTIFIED is IBHS’s voluntary construction and re-roofing standard. It has a multifamily program that covers condominiums where occupants own or lease only the interior (IBHS), and a Fairhope, Alabama condominium project received a FORTIFIED Commercial Hurricane Gold designation in 2018 (IBHS). A designated roof or building gives an underwriter documented evidence of wind resistance, and that strengthens a submission.
Be careful about assuming a discount. The Alabama state grant program, Strengthen Alabama Homes, excludes condominiums by rule (ALDOI Rule 482-1-159), and any premium credit for a commercial or condo FORTIFIED designation is set by the carrier, not by a statewide schedule we can quote. Ask your carrier in writing before you budget for one.
How should a condo board handle valuation and reserves?
Insured value drives both the premium and the deductible, so an outdated value hurts twice: it understates the rebuild cost, and a percentage deductible applied to a low value looks smaller than it will feel against actual repair costs. Get a current valuation, document roof age and openings protection, and keep the inspection and maintenance records together. See how replacement cost is set.
Then decide the deductible on purpose. Compare what each deductible level saves in premium against what reserves and owners can fund after a storm. Owners’ HO-6 loss assessment limits are often small, so a deductible assessment can land mostly on owners’ own pockets. Flood is separate: the wind policy excludes it, and NFIP condo coverage is capped per unit, so excess flood is a board decision to make with numbers in front of it.
Common questions
Is our Gulf Shores condo association required to carry flood insurance?
A lender requires it only for buildings in a Special Flood Hazard Area, but the wind policy excludes flood regardless of the map. Sally's surge and rainfall in Baldwin County show why many boards buy it anyway. We price the NFIP layer and private excess together.
Can an Orange Beach condo association get coverage from the AIUA?
The AIUA writes wind and hail only policies for property south of the 31st parallel in Baldwin and Mobile counties, for owners who cannot get standard coverage. Whether a particular building qualifies, and at what limit, is the AIUA's decision, so we confirm before building a program around it.
Do you work with associations in Fairhope, Perdido Key, or Dauphin Island?
Yes. We are based in Birmingham, Alabama and place coastal condo programs across the Gulf and Atlantic coasts. Send the schedule of values, loss runs, and expiring policy and we will tell you what the account needs.
Surplus lines insurers are not licensed (“admitted”) in Alabama, and policies they issue are not protected by the Alabama Insurance Guaranty Association if the insurer becomes insolvent. Surplus lines placements are generally made only after admitted markets have been considered, as state law requires.
This article is for general educational purposes only. It isn't legal, tax, accounting, or lending advice and doesn't create a producer–client relationship. Policy terms, exclusions, and availability vary by carrier, state, and property. Only the policy actually issued determines coverage. Regulatory and lender requirements change; confirm current rules with your attorney, lender, or servicer before relying on anything here.
Free renewal review
Send your coastal condo renewal date
We'll reply within one business day with when to start marketing it and what to have ready. Built for accounts with $50,000+ in annual premium.
- A second set of expert eyes on your program, free.
- Marketed to the carriers that actually want your risk.
- No obligation, fully confidential.
Book 20 minutes or call (205) 999-4884