Builders Risk & Owner-Controlled Insurance Programs (OCIP)
Builders risk and wrap-up (OCIP) programs for ground-up and value-add projects from $25M to $100M+.
By Dan Wentz, commercial real estate insurance broker · Updated
On a big development, insurance structure is one of the few budget lines you can actually move.
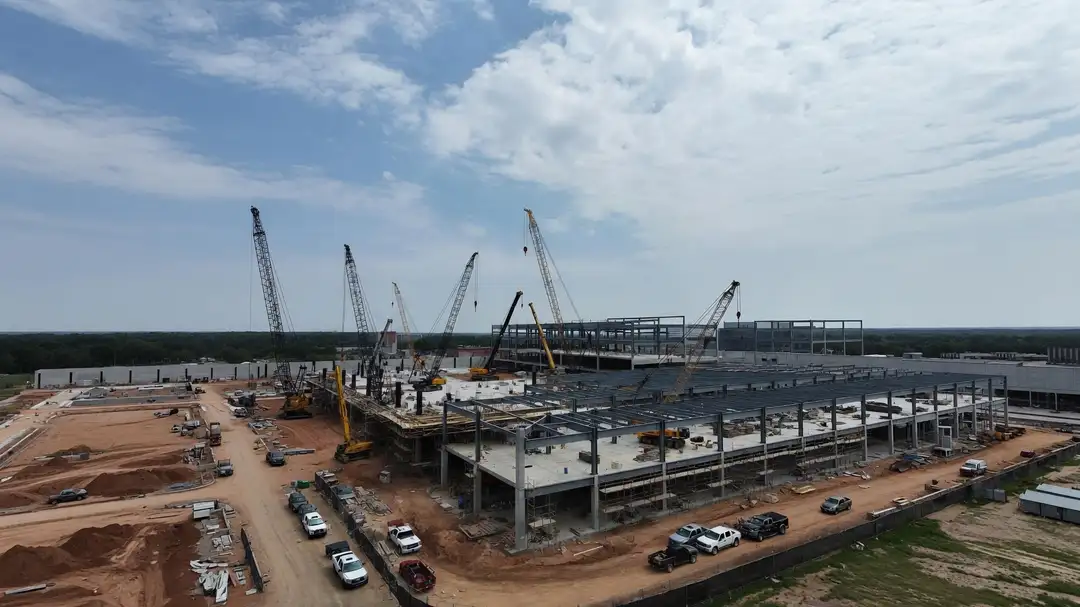
Builders risk covers the course of construction on any project.
On larger jobs, an owner-controlled insurance program (an OCIP, or wrap-up) also pulls general liability, excess, and workers' comp under one owner-controlled master, which strips the duplicated insurance markup out of every trade's bid and closes the gaps between contractors' policies. It also puts you, not your GC, in control of claims and limits. We design the program up front and administer it all the way through substantial completion.
Who this is for
Built for accounts like yours
Coverage
What we structure
Builders risk
Course-of-construction property including soft costs, delay in completion, and catastrophe perils on exposed sites.
Owner-controlled program (OCIP)
GL, excess, and workers' comp for every enrolled trade on the project, controlled by the owner instead of scattered across subcontractors.
Excess / umbrella towers
Project-specific excess limits built to what the loan documents and contracts require.
Program administration
Enrollment, payroll audits, and closeout, managed until the last certificate clears.
Compared
OCIP vs. builders risk: what's the difference?
They are not alternatives. Builders risk is first-party property coverage for the structure while it is under construction. An OCIP or CCIP is a wrap-up program that centralizes the contractors' general liability and workers' comp, and in some programs excess liability, for one project. Most large projects carry both.
| Topic | Builders risk | OCIP / CCIP (wrap-up) |
|---|---|---|
| What it covers | Physical loss to the building and materials under construction, usually with soft costs and delay in completion. | General liability and workers' comp for enrolled contractors, and in some programs excess liability, on one project. |
| Type of coverage | First-party property. | Third-party liability and workers' comp. |
| Who buys it | The owner or the general contractor, as the construction contract requires. | The owner (OCIP) or the general contractor (CCIP). |
| Who is insured | Owner, general contractor, and subcontractors, with the lender as loss payee. | Enrolled contractors and subcontractors, with the owner and lender as additional insureds. |
| Policy term | The construction period, with extensions if the schedule slips. | The construction period, plus a completed-operations tail after the work is finished. |
| What it doesn't cover | Liability claims and workers' comp. Named storm, flood, and quake are often sublimited or excluded unless added. | Damage to the building itself. Pollution, professional liability, auto, equipment, and contractors' off-site work are usually outside a wrap-up. |
| How it's priced | A rate on the completed project value, which includes hard and soft costs. | Based on project cost or enrolled payroll. The owner pays for an OCIP directly; a CCIP is built into the contractor's price. |
| When it makes sense | Nearly every project with a physical-damage exposure. | Larger projects with many trades, where one administered program is worth the effort. |
CCIP vs. OCIP is a control question. Under an OCIP, you choose the carriers and limits and direct claims. Under a CCIP, the general contractor does, and the cost sits inside the contract price.
Tools & guides
Tools and guides for this asset class
Guide
Builders Risk to Permanent Checklist
When builders risk ends, how to reset values to replacement cost, when business income starts, and what the lease and permanent loan require at closeout.
Read the checklistFree tool
Coinsurance Penalty Calculator
Free, no email required: a coinsurance clause cuts every claim, not just a total loss, when the limit trails replacement cost. See the exact payout on your loss, the penalty across loss sizes, and what it takes to cure the gap, plus the margin clause that replaces it on blanket programs.
Run your numbersGuide
Certificate of Insurance Guide
What a COI does and doesn't do, additional insured endorsements, and a checklist for reviewing the certificate a contractor hands you.
Read the guideFAQ
Common questions
OCIP or builders risk: which do I need?
Builders risk, always: it covers the course-of-construction property on virtually every project. The OCIP question is about size. Once hard cost clears roughly $25M, consolidating GL, excess, and workers' comp under the owner starts paying for itself in stripped-out markup and claim control. We model both and show you the break-even.
How big does a project need to be for a wrap-up?
Rule of thumb: GL-only wrap-ups start earning their keep around $25M of hard construction cost, and full OCIPs are common on $50M-$100M+ projects. Below that, a well-structured builders risk plus contractor-placed coverage usually wins on cost.
Does an OCIP replace builders risk?
No. An OCIP covers contractors' liability and workers' comp, not the building. Damage to the structure and materials under construction is a builders risk loss, so a project with an OCIP still needs a builders risk policy.
What's the difference between an OCIP and a CCIP?
Who controls the program. In an OCIP the owner buys and administers the wrap-up and chooses the carriers and limits. In a CCIP the general contractor does, and the cost is built into the contract price.
Can you coordinate with our lender and equity requirements?
Yes. Limits, additional insureds, waivers, evidence of coverage: we build the program to the loan and joint-venture requirements from day one and keep it compliant through completion, so insurance is never the reason a draw or a closing stalls.
Coverage described on this page is a general summary, not a quote, coverage recommendation, or offer of insurance. Requesting a quote doesn't bind coverage. Terms, exclusions, and availability vary by carrier, state, and property, and only the policy actually issued determines coverage. Insurance is placed through producers licensed in the state where the property is located.
Free renewal review
Talk to a builders risk / OCIP specialist
We'll reply within one business day with when to start marketing it and what to have ready. Built for accounts with $50,000+ in annual premium.
- A second set of expert eyes on your program, free.
- Marketed to the carriers that actually want your risk.
- No obligation, fully confidential.
Book 20 minutes or call (205) 999-4884